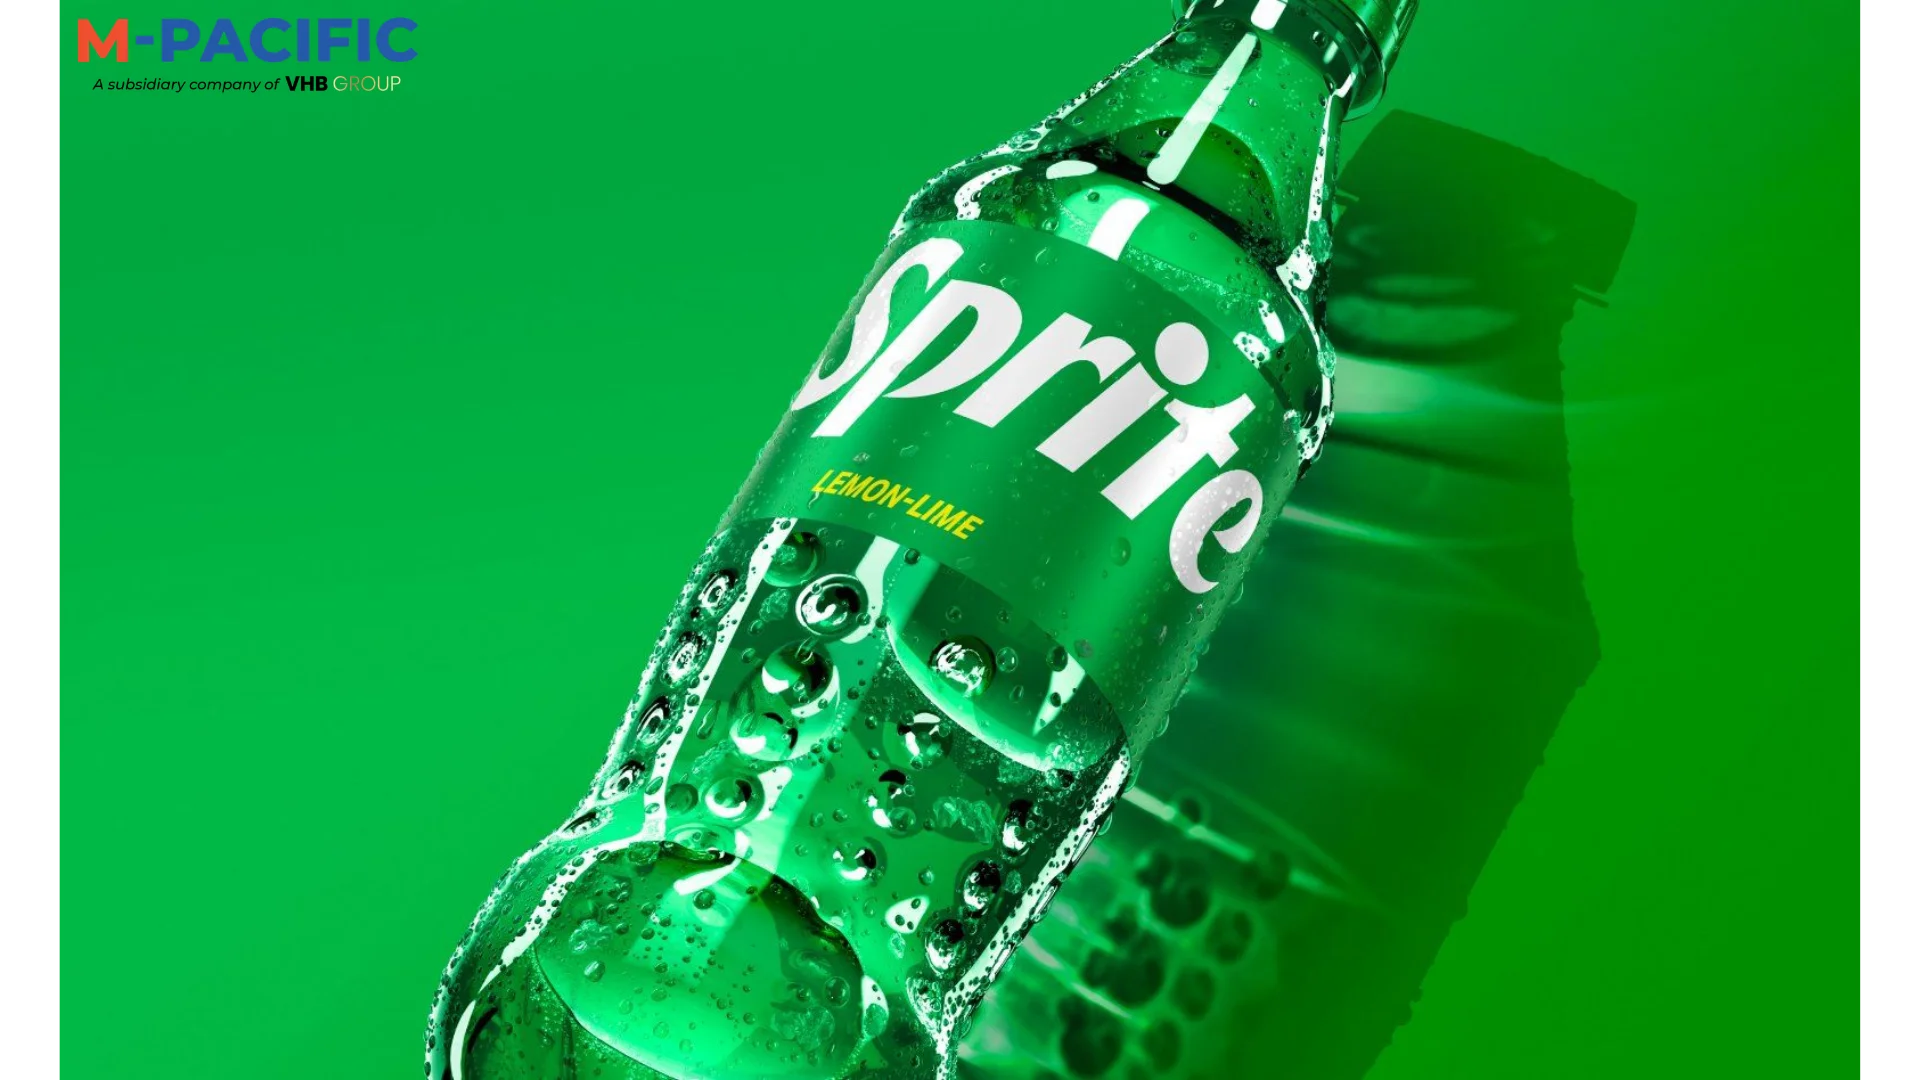
Analyzing the Sprite Soft Drink Distribute Channel Network provides a detailed roadmap for how one of the world’s premier carbonated soft drink brands achieves pervasive market availability. For FMCG sales directors, wholesale importers, and retail category managers, understanding Sprite’s route-to-market (RTM) strategy reveals how multi-tiered distribution networks move high-velocity stock from bottling facilities to urban hypermarkets and traditional trade outlets.
Table of Contents
- Analyzing the Multi-Tiered Sprite Route-to-Market (RTM) System
- Direct Store Delivery (DSD) vs. Centralized Warehouse Distribution
- Retail Channel Matrix: Modern Trade, Convenience, Traditional Trade, and HoReCa
- Capillary Integration in Emerging Markets (Micro-Distribution Centers)
- Digital Restocking Engines, Predictive Ordering, and Fleet Logistics
- Frequently Asked Questions (FAQ)
1. Analyzing the Multi-Tiered Sprite Route-to-Market (RTM) System
The distribution strategy of The Coca-Cola Company relies on a hybrid execution model that balances global brand management with localized bottling and distribution systems:
- Primary Production & Bottling Stage: Centralized Coca-Cola concentrate plants supply licensed anchor bottlers (such as CCEP, Swire, or FEMSA).
- Wholesale & Master Distribution Tier: Anchor bottlers operate Direct Store Delivery (DSD) fleets for key accounts and supply master FMCG consolidators for international trade.
- Last-Mile Retail Execution: Product flows directly into supermarket chillers, convenience forecourts, vending machines, and traditional neighborhood outlets.
2. Direct Store Delivery (DSD) vs. Centralized Warehouse Distribution
Sprite Soft Drink Distribute Channel Network utilize two main physical distribution channels to service retail points:
Direct Store Delivery (DSD)
Under the DSD model, local bottling partners operate dedicated delivery fleets that transport stock directly from bottling facilities to retail store shelves. Sales representatives manage shelf display setup, stock rotation (FIFO), and localized promotional activations.
- Primary Advantage: Guarantees prime chiller visibility, eliminates retail backroom storage gridlock, and ensures pristine product presentation in high-volume convenience chains.
- Trade-Off: Incurs higher operational fleet costs and requires localized labor density.
Centralized Warehouse Distribution
Under centralized warehouse distribution, soft drink stock is shipped in full truckloads (FTL) or full container loads (FCL) to supermarket distribution centers, cash-and-carry hubs, or national retail logistics centers.
- Primary Advantage: Significantly lowers logistics distribution costs per unit, enabling bulk volume discounting for major hypermarket chains.
- Trade-Off: Shifts store-level merchandising and inventory handling responsibilities to the retailer.

3. Retail Channel Matrix: Modern Trade, Convenience, Traditional Trade, and HoReCa
Different retail channels require tailored logistics setups, packaging formats, and delivery frequencies:
| Retail Channel | Target Outlets | Dominant Packaging SKUs | Delivery Model | Relative Gross Margin |
| Modern Trade | Hypermarkets, Supermarkets | 12-Packs, 1.5L/2.0L PET | Central Warehouse Distribution | Standard Volume Margins |
| Convenience & Forecourt | Gas Stations, Express Stores | 330ml Sleek Cans, 500ml PET | DSD / Frequent Replenishment | High Margin per Unit |
| Traditional Trade | Mom-and-Pop Shops, Kiosks | Single Cans, Returnable Glass | Wholesalers / Micro-Distributors | Moderate Volume Margins |
| HoReCa & Food Service | Fast Food, Hotels, Venues | Contour Glass, Fountain Syrup | Specialized Food Service Reps | Premium Service Margins |
| Vending & Automated | Transit Hubs, Office Parks | 355ml Cans, 500ml PET | Automated Replenishment | Maximum Margin per Unit |
4. Capillary Integration in Emerging Markets (Micro-Distribution Centers)
Penetrating highly fragmented emerging markets requires capillary distribution networks that reach small independent retailers:
- Micro-Distribution Centers (MDCs): In densely populated urban centers or rural regions across Africa, Asia, and Latin America, independent local hubs use agile transport vehicles (pushcarts, tricycles, small pick-up trucks) to deliver product to traditional neighborhood shops that larger trucks cannot access.
- Returnable Glass Bottle (RGB) Closed-Loop Networks: In developing markets, Returnable Glass Bottle (RGB) channels remain vital. Consumers pay a deposit for heavy glass bottles, returning empty containers upon subsequent purchases, significantly lowering packaging costs per serving.
5. Digital Restocking Engines, Predictive Ordering, and Fleet Logistics
Modern Sprite distribution networks rely on advanced digital tools to optimize inventory flow:
- B2B Merchant Ordering Apps (e.g., myCoke): Proprietary mobile applications allow independent store owners to order inventory directly from their smartphones, eliminating the need for manual sales rep visits.
- Predictive Restocking Analytics: Machine learning algorithms analyze historical store-level sales data, localized weather forecasts, and regional events to auto-generate suggested restocking orders before stockouts occur.
- Dynamic Route Optimization: Fleet management software recalculates daily delivery vehicle paths based on live traffic data and store receiving windows, minimizing fuel consumption and carbon footprint per delivered case.
Sprite Distribution Network FAQ
Disclaimer: Unless otherwise stated, the images used in this article are the property of their respective owners. We do not claim ownership of any third-party images featured, and they are used here strictly for informational and educational purposes. If you are the copyright holder and wish to have an image removed, please contact us.